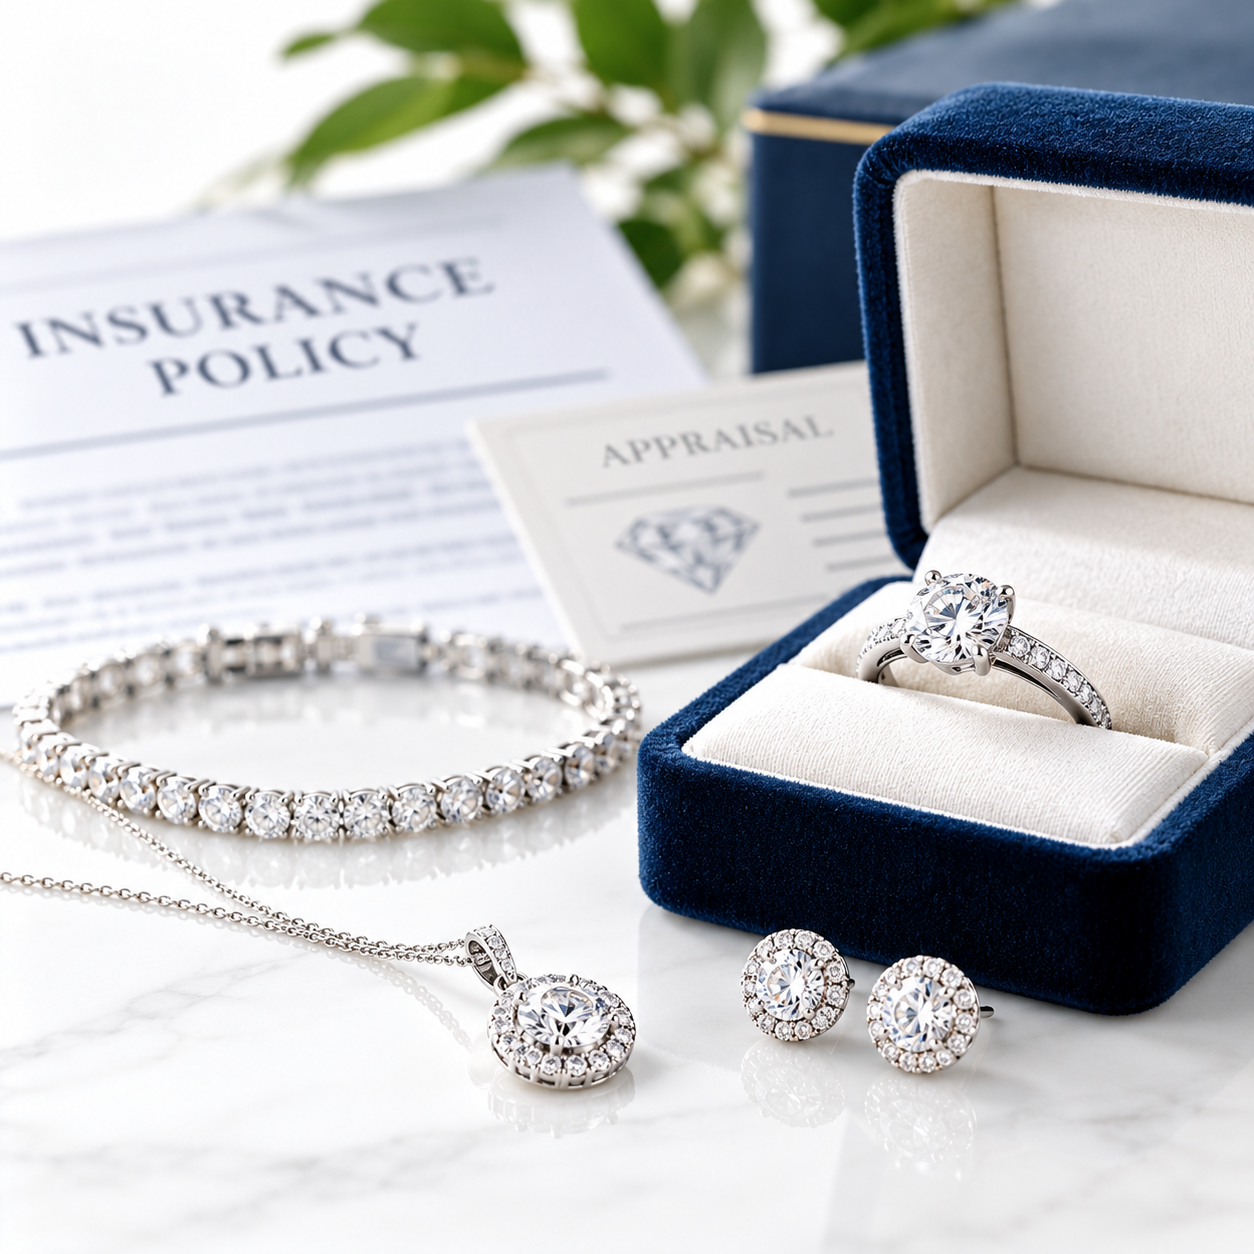
Yes, most homeowners insurance policies provide coverage for jewelry, but there can be some important limitations.
For example, your policy may cover jewelry damaged in a fire, but have a relatively low limit for theft. Some types of accidental loss, such as losing a ring while swimming or having a stone fall out of its setting, may not be covered under a standard homeowners policy.
Scheduling valuable jewelry separately can help address these limitations, often providing broader protection and, depending on the insurance company, a lower deductible or no deductible at all.
What does it mean to schedule jewelry or other valuables?
Scheduling simply means listing an item separately on your insurance policy, generally with an agreed or documented value.
This is commonly done for engagement rings, wedding bands, expensive watches, artwork, collectibles, and other valuable belongings.
Depending on the company and type of item, you may need an appraisal, receipt, or other documentation to establish its value.
What other items should I consider scheduling?
Jewelry is probably the most common, but there are plenty of other items worth considering.
Artwork, antiques, collectibles, musical instruments, expensive bicycles, and even golf equipment may benefit from additional coverage.
Not every item needs to be scheduled. The important thing is understanding what your homeowners policy already covers and where additional protection might make sense.
What happens if I no longer own something that's scheduled?
This is something we see from time to time.
Maybe you sold a piece of jewelry, gave something to a family member, replaced an expensive bicycle, or simply forgot an item was listed on your policy.
If you're still paying to insure something you no longer own, it's probably time to remove it.
That's why we encourage occasionally reviewing your scheduled personal property. You might be surprised what's still listed.
Should I update the values of my scheduled items?
It's certainly worth reviewing.
Jewelry, artwork, and collectibles can change in value over time. An appraisal from several years ago may not accurately reflect today's replacement cost.
Some insurance companies periodically require updated appraisals, while others may not.
It's a good idea to review your scheduled items and their insured values with your agent to determine whether any changes are appropriate.
What's the takeaway?
Your homeowners insurance provides important protection for your belongings, but it isn't necessarily designed to cover every valuable item in every situation.
Take a few minutes to review what you own, what's scheduled separately, and whether the coverage still makes sense.
If you're unsure what's listed on your policy or have something valuable you'd like to protect, we're happy to review your options.
Mike & Jenn Barrett
Barrett Insurance Agency, LLC
Coverage, limits, deductibles, and exclusions vary by policy and insurance company. Scheduling an item does not guarantee coverage for every cause of loss.
Below are a few of the amazing carriers we proudly partner with!
"Good Policies"
Insurance doesn't have to be boring! Join Mike Barrett on Magic 97.7 Tuesdays at 8:35 AM and Kix 105.5 WKXH Wednesdays at 7:50 AM for helpful tips, straight talk, and a little humor along the way.


| |
229 Portland St, Suite 101
St. Johnsbury, VT 05819-2040